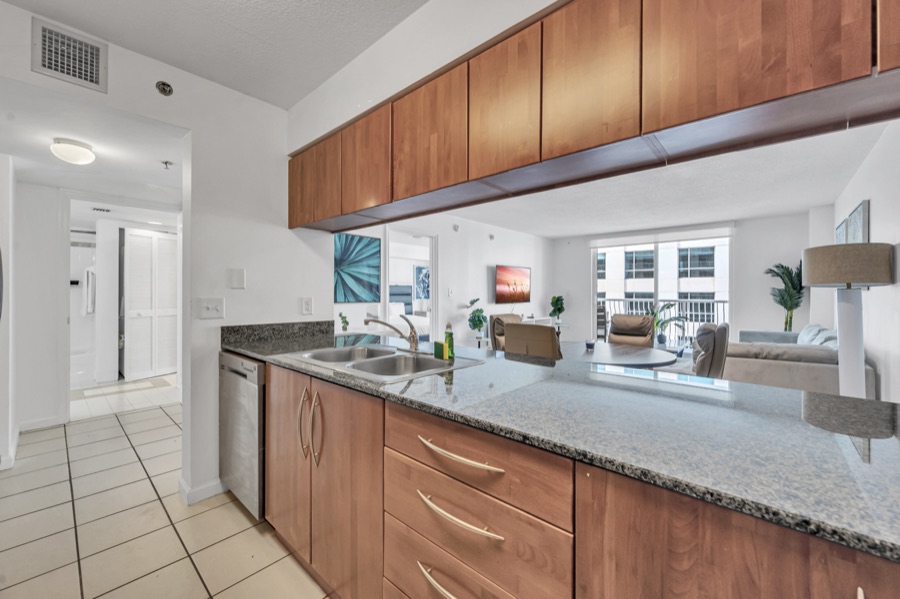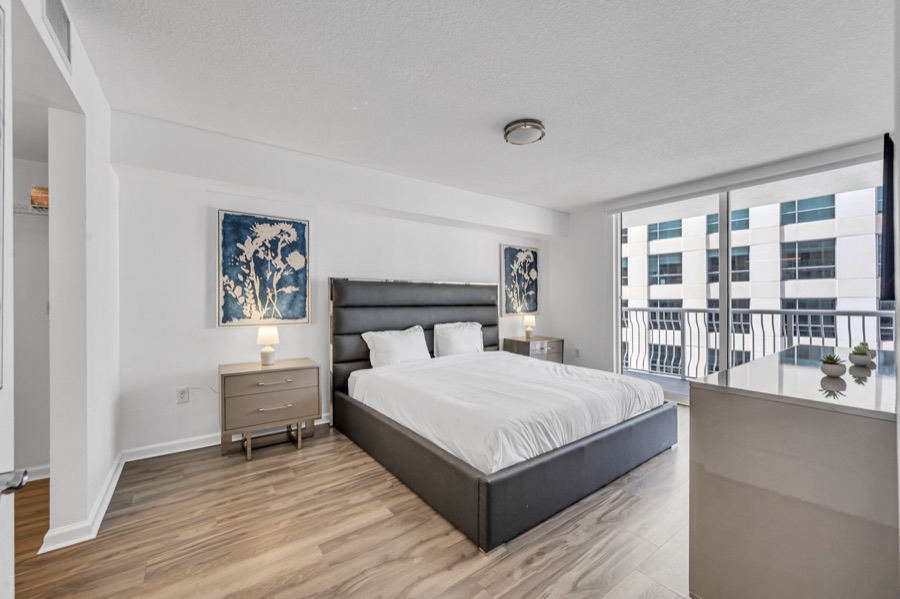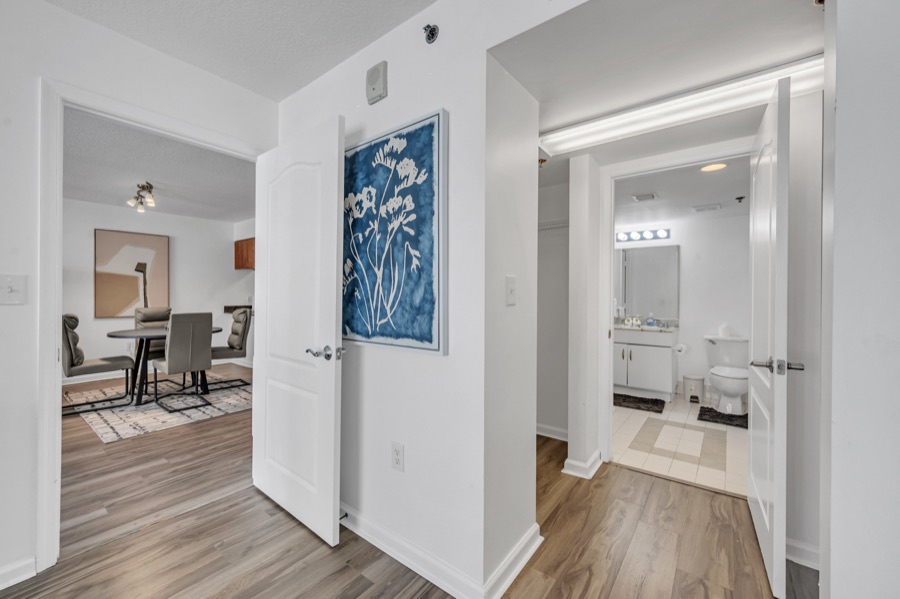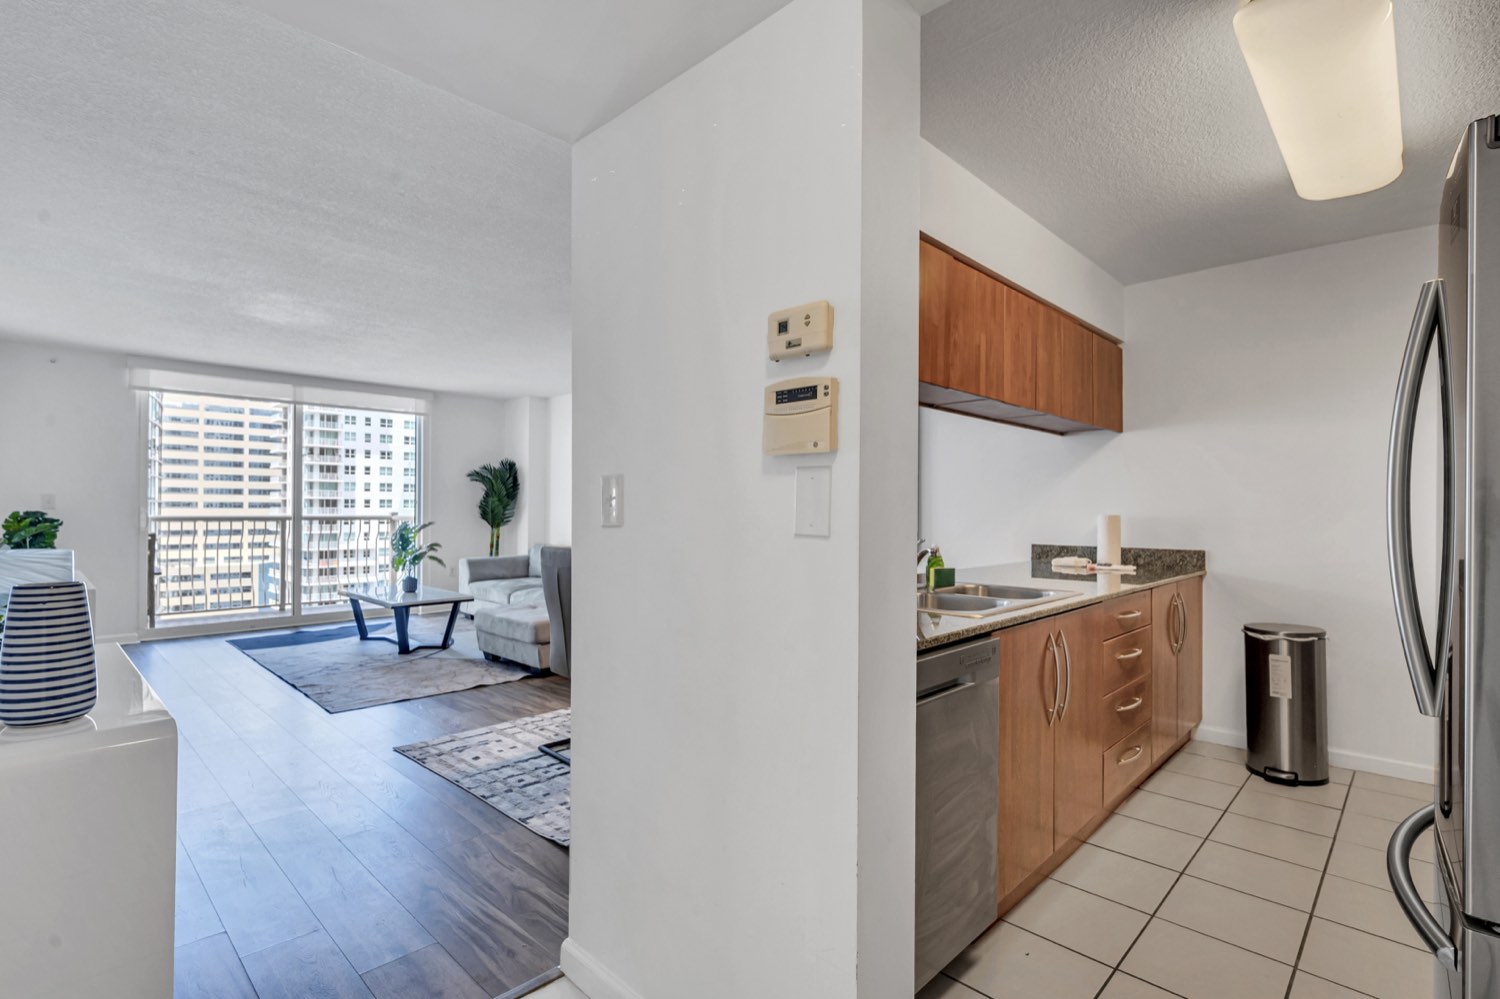
The city ordered The Club's association to stop stays under 30 days, saying the building lacks the certificate of use for transient lodging; the association contests the order. In late October 2026 the city issued a notice of violation for use not in compliance with the certificate of use and mailed a citation to the association's board, with a Code Enforcement Board hearing reported as tentatively set for 9 December 2026 (CBS Miami and The Real Deal, 23 October 2026). No ruling had been published when we checked on 14 November 2026. The income below is what units in the building earned; ask us for the status the week you make an offer.
Not a vacant flip — a tenant is in place today, on a lease from the current owner. The STR numbers below start once that lease ends.
| Current tenant, in place | $2,950/mo |
| Lease renewed | July 14, 2026 |
| Owner-added termination clause | 60 days' notice |
| Furniture | Tenant's — not included |
The lease itself just renewed, but the owner secured a 60-day termination clause — so a buyer can take possession within 60 days of closing, roughly September 2026, well ahead of #2608 (Nov 2026), #3018 (Feb 2027) and #1914 (Apr 2027). That speed is priced in: at $460,000 this is the most expensive of the four. Confirm the 60-day clause transfers to a new owner before relying on it — get it in writing from the listing agent.
Listing agent Liana Doganiero (The Keyes Company) is offering a 3% co-broke commission. Source: WhatsApp thread with the listing agent, 16–18 Jul 2026 — verify directly before writing an offer.
These aren't AirDNA guesses. They come from a 1-bedroom unit Property Management Brickell actively manages in this exact building (Guesty P&L, 12-month trailing May 2025 → April 2026). The important nuance: that owner self-occupied it every summer, which held its reported revenue below its true rental potential.
| Managed 1BR at The Club — as reported | Trailing 12 mo |
| Occupancy (blended) | 73% |
| Average daily rate | $192 |
| Gross revenue as reported | $52,100 |
May–August, that unit ran just 45–54% occupancy while the other professionally-managed units in the same building held 80–90%. That gap is owner self-use, not weak demand. As a pure investor keeping the unit fully available, the previous owner's foregone summer rent — about $6,400/year — comes back to you.
| Same unit — investor basis (summer restored to building-market ~80%) | |
| Occupancy | 83% |
| Average daily rate | $192 |
| Gross annual revenue — base case for 2304 | $58,500 |
Cross-check: the best-run unit we manage in this building, with no owner blocks, ran 86% occupancy on a larger floorplan — above our 83% base assumption. 2304 is also larger (825 vs 780 sq ft) with direct bay views, further supporting the figure.
Professionally-managed short-term rental. Base revenue $58,500 (managed comp, owner summer-blocks restored to market).
| Gross STR revenue | $58,500 |
| Professional STR management (20%) | −$11,700 |
| HOA ($706 × 12) | −$8,472 |
| Property tax | −$6,411 |
| Insurance (condo, STR) | −$2,000 |
| Utilities + internet | −$2,640 |
| Supplies, turnover, reserves (~4%) | −$2,340 |
| Net operating income (NOI) | $24,900 |
| Debt service — Club mortgage ($345K @ 7.25%) | −$28,248 |
| Debt service — home-equity line ($131K @ 12%, IO) | −$15,720 |
| Pre-tax cash flow | −$19,035 (−$1,586/mo) |
At 100% financing — a 7.25% mortgage plus a 12% home-equity line — the deal is cash-flow negative by about $1,600/month. The 5.4% cap rate sits well below the blended cost of that debt, and the 12% line is the reason: it carries a quarter of the purchase at more than double the property's own yield. This is not a small gap that better management closes. The return here has to come from equity build + appreciation — and at 12%, read the wealth breakdown below before you decide it does.
Same $460K, same 100% financing (7.25% mortgage + 12% equity line). Only the STR revenue assumption changes — and note that no revenue case gets to break-even. That is the 12% line, not the property.
Cash flow is only one line. On a 100%-financed asset, the wealth is built through principal paydown and appreciation on a bay-front Brickell property.
At 8.5% the paydown and appreciation covered the negative carry and left roughly +$2,760. At 12% the extra $4,585 of annual interest overruns them: year one is −$1,822, even with 3% appreciation doing the heavy lifting. The equity line costs more than the asset produces and more than it appreciates. If the 12% is the real cost of the money, the honest read is that this purchase does not carry itself on any of the three revenue cases — and the answer is a bigger cash down payment, a cheaper line, or a different unit.
Your Doral condo currently nets roughly +$925/month as a rental. Against this unit's −$1,586/month it covers a little under 60% — the two-property portfolio runs at about −$660/month, not break-even. And the equity line is drawn on the Doral itself, so that $925 is what is left after the line it is already paying for.
Two levers move this, and neither is management: refinancing the 12% line down to a normal home-equity rate is worth roughly +$380/month on its own, and a cash down payment instead of 100% financing turns the monthly positive outright. If the 12% is fixed and cash is not available, the honest advice is to wait rather than buy — ask me for the 25%-down version before you decide.
I'll bring in a lender to size the home-equity line precisely, and we'll walk the STR set-up and management plan for 2304. 15 minutes.
A Miami Herald investigation (July 16, 2026) and Editorial Board opinion (July 20, 2026) examined short-term rental compliance at The Club at Brickell Bay, reporting that roughly 545 of the building's 643 units operate as short-term rentals while only a small subset holds a valid city Certificate of Use for lodging. Florida law (Fla. Stat. §509.242) requires a building-wide Change of Occupancy once more than 25% of units convert to short-term use — a threshold this building has passed. A new HOA board took office in June 2026 and has stated it intends to pursue proper registration. The short-term rental revenue in this analysis reflects actual historical operating performance, not a guarantee of continued legality — buyers should independently confirm current compliance status before purchase.